Solar Panels Can Kill a Florida Closing: Five Questions to Answer Before Contract
Owned, financed, leased, or paid off through the property tax bill? Solar panels are often a separate transaction attached to the roof. Five questions to answer before going under contract.
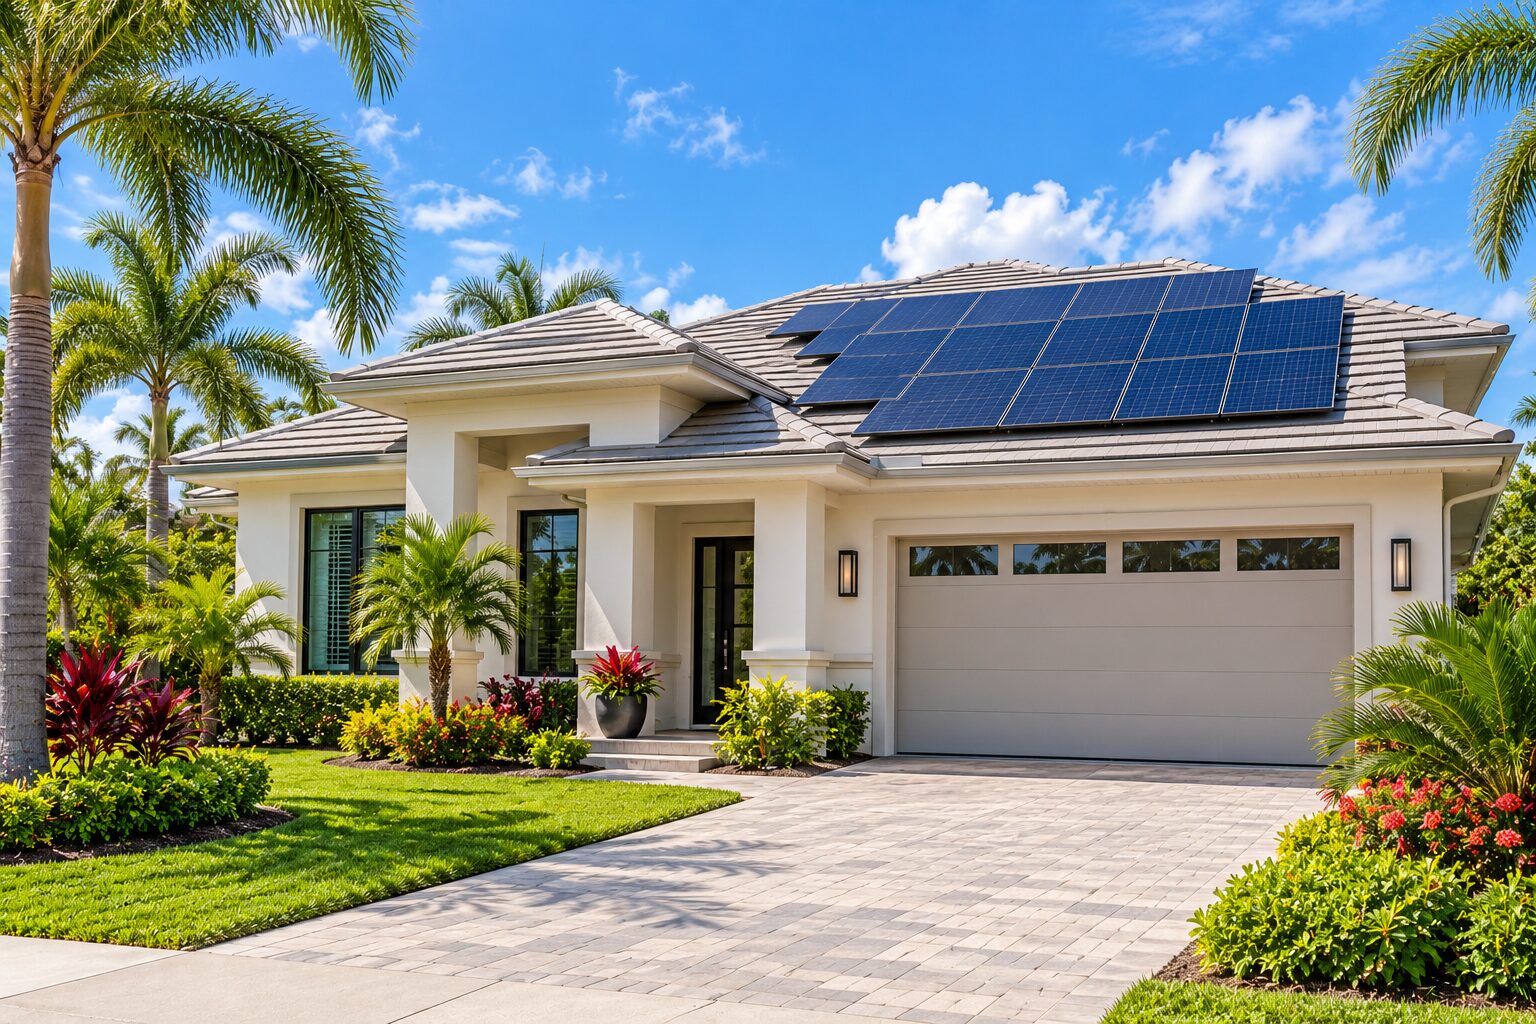
Solar panels look like part of the house. Legally and financially, they are often part of an entirely separate transaction — one with its own lender, its own contract, its own approval process and sometimes its own lien.
Which is why the worst possible time to ask who owns the system is a week before closing.
The Florida Realtors/Florida Bar Residential Contract and its AS IS version convey existing improvements and fixtures unless they are specifically excluded, and rooftop solar ordinarily qualifies. But saying the panels convey does not establish that the seller actually owns them, or that the seller can transfer them free of a loan, lease or assessment. Those are two different questions, and only one of them is answered by the contract form.
Step One: Identify the Arrangement Before the Listing Goes Live
There are four common structures in Southwest Florida, and each one creates a different set of title, lending and contract problems.
1. Owned outright
The cleanest scenario. The panels are the seller’s property, free of financing, and they convey with the house. Even here, confirm there is no UCC fixture filing — a public record a lender files to claim equipment attached to a house — left over from an old loan that was paid but never terminated. A stale filing is a title exception, and it has to be released.
2. Purchased with solar financing
The most common source of last-minute closing failures. The seller should pull the financing agreement, the current balance, the payoff procedure and the transfer requirements — in writing, from the solar lender.
Do not rely on “the buyer can just assume it.” The solar lender may prohibit assumption entirely, may require the buyer to qualify on its own credit standards, and may charge transfer fees. And even when the solar company approves the transfer, the buyer’s mortgage lender is a separate gatekeeper: it may refuse the obligation outright, or count the monthly payment in the buyer’s debt-to-income ratio and shrink the loan the buyer qualifies for.
3. Lease or power-purchase agreement
Here the seller does not own the equipment at all. A solar company owns the panels and either leases them to the homeowner or sells the homeowner the electricity they produce, which is called a power-purchase agreement. The same early review applies: can the agreement be transferred to the buyer, must the buyer qualify, how many years remain, and what does early termination cost? Those documents frequently also govern maintenance obligations, insurance requirements, removal rights and the rate the homeowner pays per kilowatt-hour — which may escalate annually.
A twenty-year escalating agreement is a material economic term of the purchase. It belongs in front of the buyer during the inspection period, not at the closing table.
4. PACE assessment
This one is different in kind, not just degree. PACE (Property Assessed Clean Energy) financing is a loan for energy improvements that is repaid through the property tax bill instead of a monthly payment to a lender. In Florida it is collected as a non-ad valorem assessment — a flat charge on the tax bill, not one based on the property’s value — and the recorded financing agreement creates a lien with the same priority as county taxes, which generally puts it ahead of any mortgage.
Two consequences follow. First, if an unpaid balance exists, Florida law requires the seller to give the buyer a statutory written disclosure at or before execution of the sales contract. Second, many mortgage lenders will simply refuse to close behind that lien and will require the assessment to be satisfied or released. That is a payoff the seller has to fund out of proceeds, and it needs to be known before the seller agrees to a price and a set of concessions.
The Five Questions to Ask Before the Property Goes Under Contract
Who owns the panels, inverters, batteries and related equipment?
Is there a loan, lease, power-purchase agreement or PACE assessment attached to the system?
What is the exact payoff or transfer process — including approval standards, fees and deadlines?
Is there a recorded lien, assessment or UCC fixture filing that has to be released at or before closing?
Will the buyer’s mortgage lender and property insurer accept the arrangement, and who bears any roof, removal or reinstallation cost?
Answers should come from the governing documents, written payoff statements, public records and the companies themselves. Not from a utility bill, and not from the seller’s recollection of what the salesperson said in 2021.
Make the Contract Fit the Facts
Once you know the structure, the contract has to reflect it.
If the seller is going to pay the system off at closing, the seller needs enough proceeds to do it, a reliable payoff statement with a good-through date, and whatever release or termination statement the title agent will require to clear the record.
If the buyer is going to take over the obligation, the contract should address document delivery, the application deadline, who applies, third-party approval, transfer fees, and — most importantly — what happens if approval is delayed or denied.
“Buyer to assume solar” is almost never enough language. It does not say whether closing is contingent on approval. It does not say when approval must occur. It does not say what happens to the deposit if the solar company or the mortgage lender says no. Three sentences of drafting at contract time prevents a deposit dispute at closing time.
Do Not Forget the Roof
Panels sit on a roof with a finite life. If the roof needs replacement in five years, someone has to pay to remove and reinstall the array, and that cost is real — often several thousand dollars on top of the roof itself. Removal may also affect the panel warranty, the roof warranty, or both.
Confirm who holds the equipment and workmanship warranties, whether they transfer to a new owner, and whether the original roof penetrations were properly permitted and inspected. Unpermitted solar installation is its own problem, and it tends to surface during the buyer’s permit search rather than during the walk-through.
Who Should Do What
Listing agents should collect the solar documents before marketing the property, the same way they collect the HOA documents. Buyer’s agents should forward those documents to the lender, the insurer and the closing agent in the first week of the contract, not the last.
And neither side should represent that a system is owned, assumable, transferable, lien-free or guaranteed to produce savings without verification. Statements about solar savings are a particularly common source of post-closing complaints, because the projected production number in a sales brochure is not a promise anyone can keep.
Solar can be an energy feature, a consumer debt, a twenty-year contract and a title issue all at once. Sorting out which one you are dealing with before the property goes under contract is what keeps it from becoming a closing that dies on the table.
Frequently Asked Questions
Do solar panels automatically convey with a Florida home sale?
Under the standard Florida Realtors/Florida Bar contracts, existing improvements and fixtures convey unless excluded, and rooftop panels ordinarily qualify. But conveyance is not the same as clear title. If the system is leased, financed or subject to a PACE assessment, the contract language alone does not resolve who owns it or what has to be paid.
Can a buyer assume the seller’s solar loan?
Sometimes, and never automatically. The solar lender sets its own approval standards and fees, and the buyer’s mortgage lender independently decides whether it will accept the obligation and how it affects qualification. Both approvals should be obtained in writing, with deadlines built into the contract.
What is a PACE assessment and why does it complicate a sale?
PACE financing for qualifying improvements is repaid through a non-ad valorem assessment collected with property taxes, and the recorded agreement carries lien priority comparable to taxes and assessments. Florida requires written disclosure to the buyer at or before contract when a balance remains, and many mortgage lenders require it to be paid off or released before they will close.
Who pays to remove the panels when the roof is replaced?
Whoever the contract says — which is why it should say. Absent an agreement, the cost falls on the owner at the time. This is worth negotiating expressly when the roof is near the end of its life.
What if the seller did not disclose the solar lease until after contract?
That depends on the structure, the timing and what was represented. A lease or financed system is generally a material fact, and a PACE balance carries its own statutory disclosure requirement. A buyer in that position should have the contract, the disclosure timeline and the solar documents reviewed before the inspection or financing deadlines expire.
Talk to a Southwest Florida Real Estate Attorney
Prell Spearing Law Firm handles residential and commercial real estate transactions, title and lien issues, and contract disputes throughout Lee, Collier, Charlotte and Sarasota Counties. Irina Prell is both a licensed Florida attorney and a licensed Florida general contractor, which matters when a deal turns on roof penetrations, permits and what an installation actually involves.
If you are listing a home with solar, buying one, or already under contract and unsure what the panels are attached to, contact the firm to discuss it.
This article provides general information about Florida law as of the date of publication. It is not legal advice and is not a substitute for advice from counsel regarding a specific transaction. Case examples are composites with identifying details changed.