An escalation addendum sets how high a buyer will go. It does not decide which offer a seller must take. What triggers the formula, what proof is required, and what it does not move.
You submit an offer with an escalation addendum — a clause that automatically raises your price to beat competing offers by a set amount, up to a ceiling you choose. Your formula beats everything on the table. Then the seller accepts a different offer — and it is a lower one.
Was the seller required to take yours because the math produced more money?
No. An escalation addendum can raise the price a buyer is offering. It does not compel anyone to accept that offer. It is a pricing formula. It does not guarantee you get the house.
What the Formula Actually Does
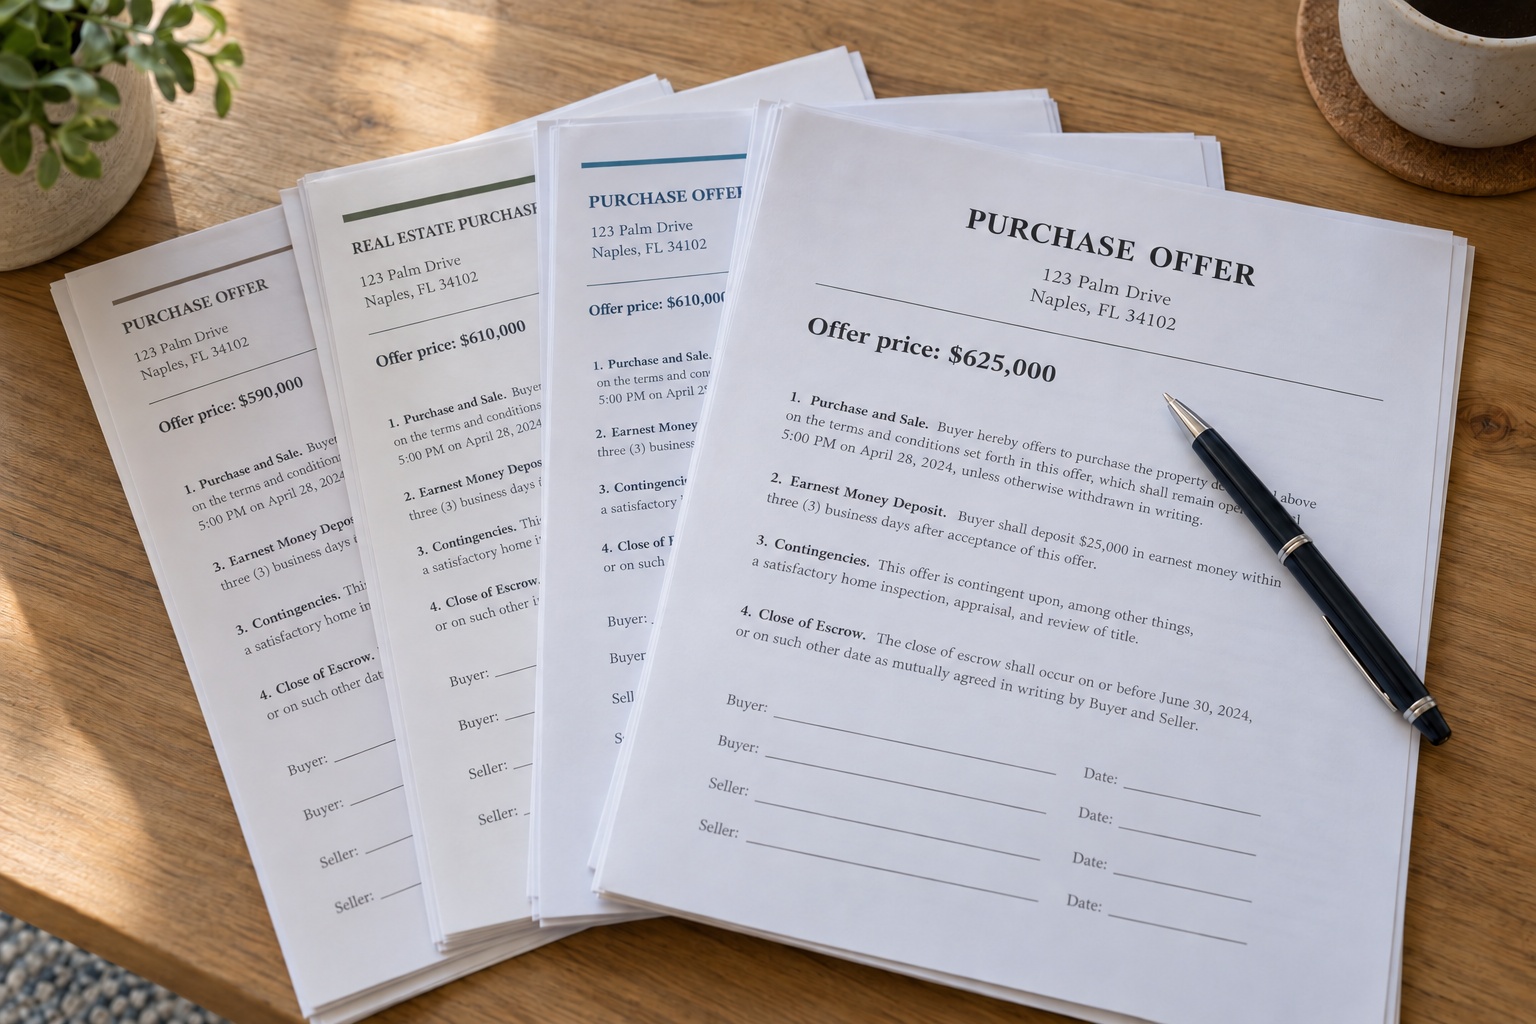
Take a buyer who offers $800,000, agrees to pay $5,000 above any competing offer, and sets a maximum price of $850,000.
A qualifying competing offer of $837,000 produces a price of $842,000.
A qualifying competing offer of $849,000 produces $850,000 — the ceiling — and the buyer’s effective increment shrinks to $1,000.
A qualifying competing offer of $860,000 produces nothing. The buyer is simply out at the ceiling.
The Florida Realtors Escalation Addendum operates only when the seller receives a competing offer that is bona fide, unexpired and acceptable to the seller. Each of those words does work.
Bona fide means genuine — not manufactured to push the escalating buyer toward the ceiling. Unexpired means the competing offer is still open for acceptance when the escalation is invoked. Acceptable means it is an offer the seller could actually accept.
Absent a qualifying competing offer, the buyer’s price does not jump to the maximum. The starting number is the number.
The Seller Can Still Take Someone Else
The seller may accept, reject, ignore or counter any offer, or call for highest and best, meaning ask every buyer for a final offer. Nothing in the form obligates a seller to select the highest escalated price.
And sellers frequently do not, for entirely rational reasons. Price is one term among many. A seller may prefer:
A lower cash offer over a higher financed one
A larger deposit
No seller credit or concession
Fewer contingencies, or a waived inspection
A shorter inspection period
A closing date that matches their next purchase
A lower offer can produce a better net and a much higher probability of actually closing. Escalating past it does not change that calculus.
The Formula Moves Price and Nothing Else
This is the part buyers misunderstand most often. The escalation changes the purchase price. It does not import the competing offer’s financing type, deposit amount, credits, inspection rights or closing date into your contract.
If the seller wants any of those terms changed, the seller has to counter, and the buyer has to accept. There is no automatic term-matching.
The Seller Can Counter Back
If the $850,000 ceiling is too low, or the buyer’s other terms do not work, the seller can counter on price, deposit, closing date, inspection rights or financing. The buyer may then accept, reject or counter again.
Here is a distinction worth keeping straight: even with no qualifying competing offer at all, a seller could simply counter at $850,000 — because the addendum told them exactly what the buyer would pay. That is an ordinary counteroffer, not an escalation. “The formula raised the price” and “the seller countered” are two different legal paths, and only one of them requires a fresh acceptance.
Which raises the obvious strategic point: an escalation addendum discloses your maximum. The Florida Realtors form permits the seller to share the buyer’s offer with potential competing buyers. Your ceiling can become the other side’s leverage.
Proof of the Competing Offer Is Not Optional
The form requires the seller to state the revised price and to provide a copy of the competing offer — with the competing buyer’s identifying information redacted — at or before written acceptance or counteroffer.
If that copy is not timely provided, the price does not increase by the escalation amount. A verbal assurance that “we have another offer at $840” does not trigger the formula, and a buyer’s agent should not advise the buyer to proceed as though it did.
Ask for the redacted copy. In writing. Before acceptance.
Financing and the Appraisal Gap
The buyer must elect whether the escalation amount will be paid in cash or financed. If neither box is selected, the form treats cash as chosen — and a buyer making that election should have proof of funds ready to accompany the offer.
A buyer financing the escalation needs to confirm lender capacity before signing, not after the formula fires. The addendum does not bind the lender, does not guarantee an appraisal, and does not waive the appraisal or financing contingency unless the buyer separately agrees to that.
Which means a perfectly valid escalation can still produce an appraisal gap — a difference between the contract price and what the lender’s appraiser says the home is worth. If the formula lands the contract at $850,000 and the appraisal comes in at $825,000, that $25,000 has to come from somewhere, and the contract determines who blinks.
An escalation addendum establishes how high a buyer is willing to go. It does not decide which complete offer a seller has to choose.
Frequently Asked Questions
Does the seller have to accept the highest escalated offer?
No. The seller may accept, reject, ignore or counter any offer, or request highest and best. The addendum sets a price mechanism; it does not create an obligation to sell to the escalating buyer.
What counts as a qualifying competing offer?
Under the Florida Realtors form, one that is bona fide, unexpired and acceptable to the seller. An expired offer, or one the seller would not accept, does not trigger the escalation.
Can the seller just tell me there was a higher offer?
Not and still escalate the price. The form requires a copy of the competing offer, with the competing buyer’s identification redacted, delivered at or before written acceptance or counteroffer. Without it, the escalation amount does not apply.
Does using an escalation addendum waive my appraisal contingency?
No. It is a separate issue. A buyer who escalates above appraised value still has whatever appraisal and financing protections the contract provides — and should confirm what those are before setting a high ceiling.
Should I use one at all?
It depends on the market and on how much you are willing to reveal. An escalation addendum tells the seller your maximum, and the seller may be permitted to share your offer with other buyers. In some situations a clean, strong single-number offer competes better.
Talk to a Southwest Florida Real Estate Attorney
Prell Spearing Law Firm reviews and drafts residential and commercial purchase contracts, addenda and counteroffers throughout Lee, Collier, Charlotte and Sarasota Counties.
If you are structuring a competitive offer, or a deal went sideways after an escalation, contact the firm.
This article provides general information about Florida law as of the date of publication. It is not legal advice and is not a substitute for advice from counsel regarding a specific transaction. Case examples are composites with identifying details changed.