The Mortgage Sandwich: Why a Wraparound Mortgage Needs More Than a Calculator
In a wraparound sale, the seller’s low-rate mortgage stays in place and the buyer pays the seller instead of a bank. Why that can backfire on both sides, and what has to be in writing.
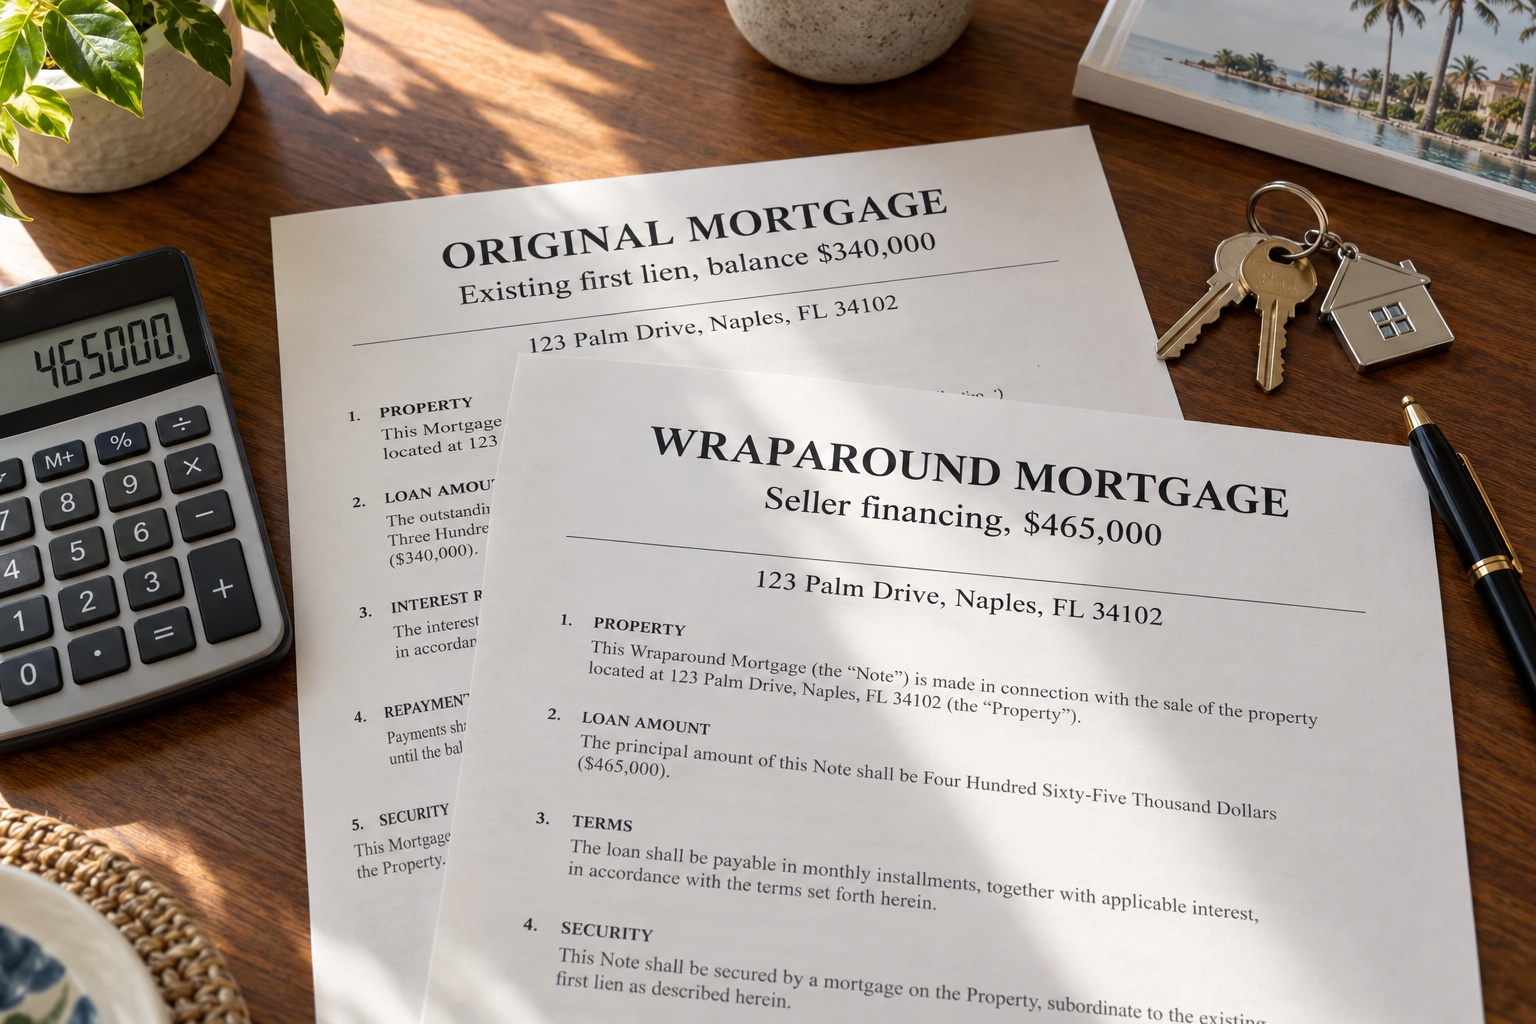
The proposal sounds elegant when someone explains it at a networking event. The seller has a mortgage at 3%. The buyer needs financing and the market is at 7%. So instead of paying off the existing loan, the seller conveys title and takes back a new note and mortgage from the buyer — while the original loan stays exactly where it is.
When prevailing rates sit well above the seller’s existing rate, the arrangement looks like a genuine win-win: below-market financing for the buyer, and a one- or two-point spread for the seller on money that is not even theirs.
It is real estate’s version of a sandwich. Unfortunately, the filling contains two debts, two borrowers, one property, and a lender that may have no idea lunch has been served.
How a Wraparound Actually Works
The buyer’s new obligation “wraps around” the existing loan, which ordinarily stays in the seller’s name and remains the seller’s personal liability. The buyer pays the seller, or a third-party servicer. Part of that payment services the underlying first mortgage; the remainder pays the seller for their equity and the rate spread.
Wrap, Assumption and Subject-To Are Three Different Things
People use these terms interchangeably. They are not interchangeable.
Assumption: the buyer formally takes over the existing debt through a process the lender controls and approves. The seller may be released.
Subject-to: the buyer takes title subject to the existing lien without ordinarily becoming personally liable to the original lender. The seller stays on the hook.
Wraparound: a new, separate debt runs from the buyer to the seller, while the seller remains liable on the original loan. Two notes exist at once.
Only one of those three involves the lender’s participation. That is the root of everything that follows.
The Lender Can Still Call the Loan
The first and largest risk is the due-on-sale clause — the standard mortgage term that lets the lender demand the full balance when the property changes hands. Transferring title generally permits the original lender to accelerate the loan, meaning call the entire remaining balance due at once.
Keeping every payment current does not extinguish that contractual right. Neither does the lender’s silence — a lender that has not noticed is not a lender that has consented, and loan servicing transfers, insurance changes and property tax records all create opportunities to notice.
So the documents have to answer the question nobody wants to ask: if the lender demands payoff, who must refinance or pay, how long do they have, and what happens if replacement financing is not available at that moment? A transaction is not protected by the parties’ shared belief that the lender probably will not find out.
The Payment Chain Cuts Both Ways
In a wrap, each party is exposed to the other’s conduct in a way that ordinary financing avoids.
If the buyer pays the seller on time every month and the seller does not forward the money to the first lender, the buyer can face foreclosure while having done everything right. The buyer’s performance does not protect the buyer’s title.
Running the other direction: if the buyer stops paying, the seller must advance the underlying payment out of pocket to keep the first loan current, protect the property and insurance, and then foreclose the wrap mortgage — a process that takes months in Florida while the seller keeps paying.
Priority Is Not Negotiable
The original mortgage remains senior, meaning it gets paid first out of any foreclosure. The seller’s wrap mortgage is junior, and it stays junior even when the wrap note carries the larger balance. A default on the first loan therefore threatens the buyer’s ownership and the seller’s security interest simultaneously.
Servicing Is Not Optional Bookkeeping
A sound wrap structure generally requires an independent servicer: a neutral party that receives the buyer’s payment, pays the underlying lender directly, and provides verifiable records to both sides. That single element removes most of the trust problem described above.
The documents should address, at minimum:
Payment verification and reporting to both parties
Who receives and forwards lender notices
Property taxes, insurance and escrow reserves
Default, notice and cure rights on both notes
Prepayment, balloon dates (a large lump sum due at the end of the term) and payoff mechanics
Release and satisfaction when the wrap is paid
Before any of that is drafted, both parties should review the actual original note and mortgage, the payment history, the escrow status and a real written payoff figure — not an estimate of what is “approximately” owed. Insurance also has to match the ownership and lien structure, which it frequently does not after a wrap.
A screenshot from a banking app is not a servicing system.
Consumer-Finance Law May Apply
Depending on the property type, occupancy, the purpose of the credit and how often the seller does these deals, federal and Florida lending rules may be triggered: disclosure requirements, ability-to-repay rules that require confirming the buyer can actually afford the loan, and licensing rules for whoever arranges it.
And a common workaround does not work: putting the buyer in an LLC does not automatically convert a consumer-purpose transaction into a business-purpose loan. Regulators and courts look at substance. If the buyer is a family moving into the house, the entity on the deed does not change what the loan is for.
What Agents Should and Should Not Do
Real estate professionals can identify the concept, recognize when a wrap might fit, and help the parties negotiate the business terms — price, rate, term, balloon, down payment.
What they should not do is build the legal structure in the additional terms box of a purchase contract. A wraparound requires coordinated purchase, title, lending, servicing, insurance and default documents drafted for the specific transaction, and a title company willing to insure it.
The arithmetic may fit on a napkin. The risk should not.
Frequently Asked Questions
Are wraparound mortgages legal in Florida?
They are not prohibited, and they are used. But legality is not the issue — the due-on-sale clause in the existing loan, consumer-finance rules, title insurability and the servicing structure are what determine whether a particular wrap is workable.
Will the existing lender find out?
Often, eventually. Deed recording, insurance changes, tax records and servicing transfers all create visibility. More to the point, a transaction whose viability depends on a lender not noticing is not a structure; it is a bet.
What happens to the buyer if the seller stops paying the first mortgage?
The first lender can foreclose against the property, regardless of the buyer’s perfect payment record to the seller. This is the strongest argument for a third-party servicer that pays the underlying lender directly.
Can the buyer just assume the seller’s low-rate loan instead?
Only if the loan is assumable and the lender approves. Some government-backed loans are; most conventional loans are not. Confirm assumability in writing with the servicer before designing anything more complicated.
Does a title company have to insure a wraparound?
No, and the answer varies by underwriter. Confirm insurability early, because discovering the problem after the parties have agreed on terms wastes everyone’s time.
Talk to a Southwest Florida Real Estate Attorney
Prell Spearing Law Firm handles seller financing, wraparound and subject-to structures, note and mortgage drafting, and the disputes that follow when these arrangements are papered badly — throughout Lee, Collier, Charlotte and Sarasota Counties.
If someone has proposed a wrap to you, on either side of the table, contact the firm before signing anything.
This article provides general information about Florida law as of the date of publication. It is not legal advice and is not a substitute for advice from counsel regarding a specific transaction. Case examples are composites with identifying details changed.